You bought a Rs 12,000 jacket, returned it, and Rs 12,000 came back. How much did you spend on clothes this month? The obviously correct answer is nothing — and yet the default behaviour of most ledgers is to report Rs 12,000 of clothing spending and Rs 12,000 of income, which is wrong twice in the same transaction.
The short answer
A refund is negative spending in the original category. Not income. Not a transfer. The purchase is being partially or wholly undone, and the entry should undo it in the same place it was made.
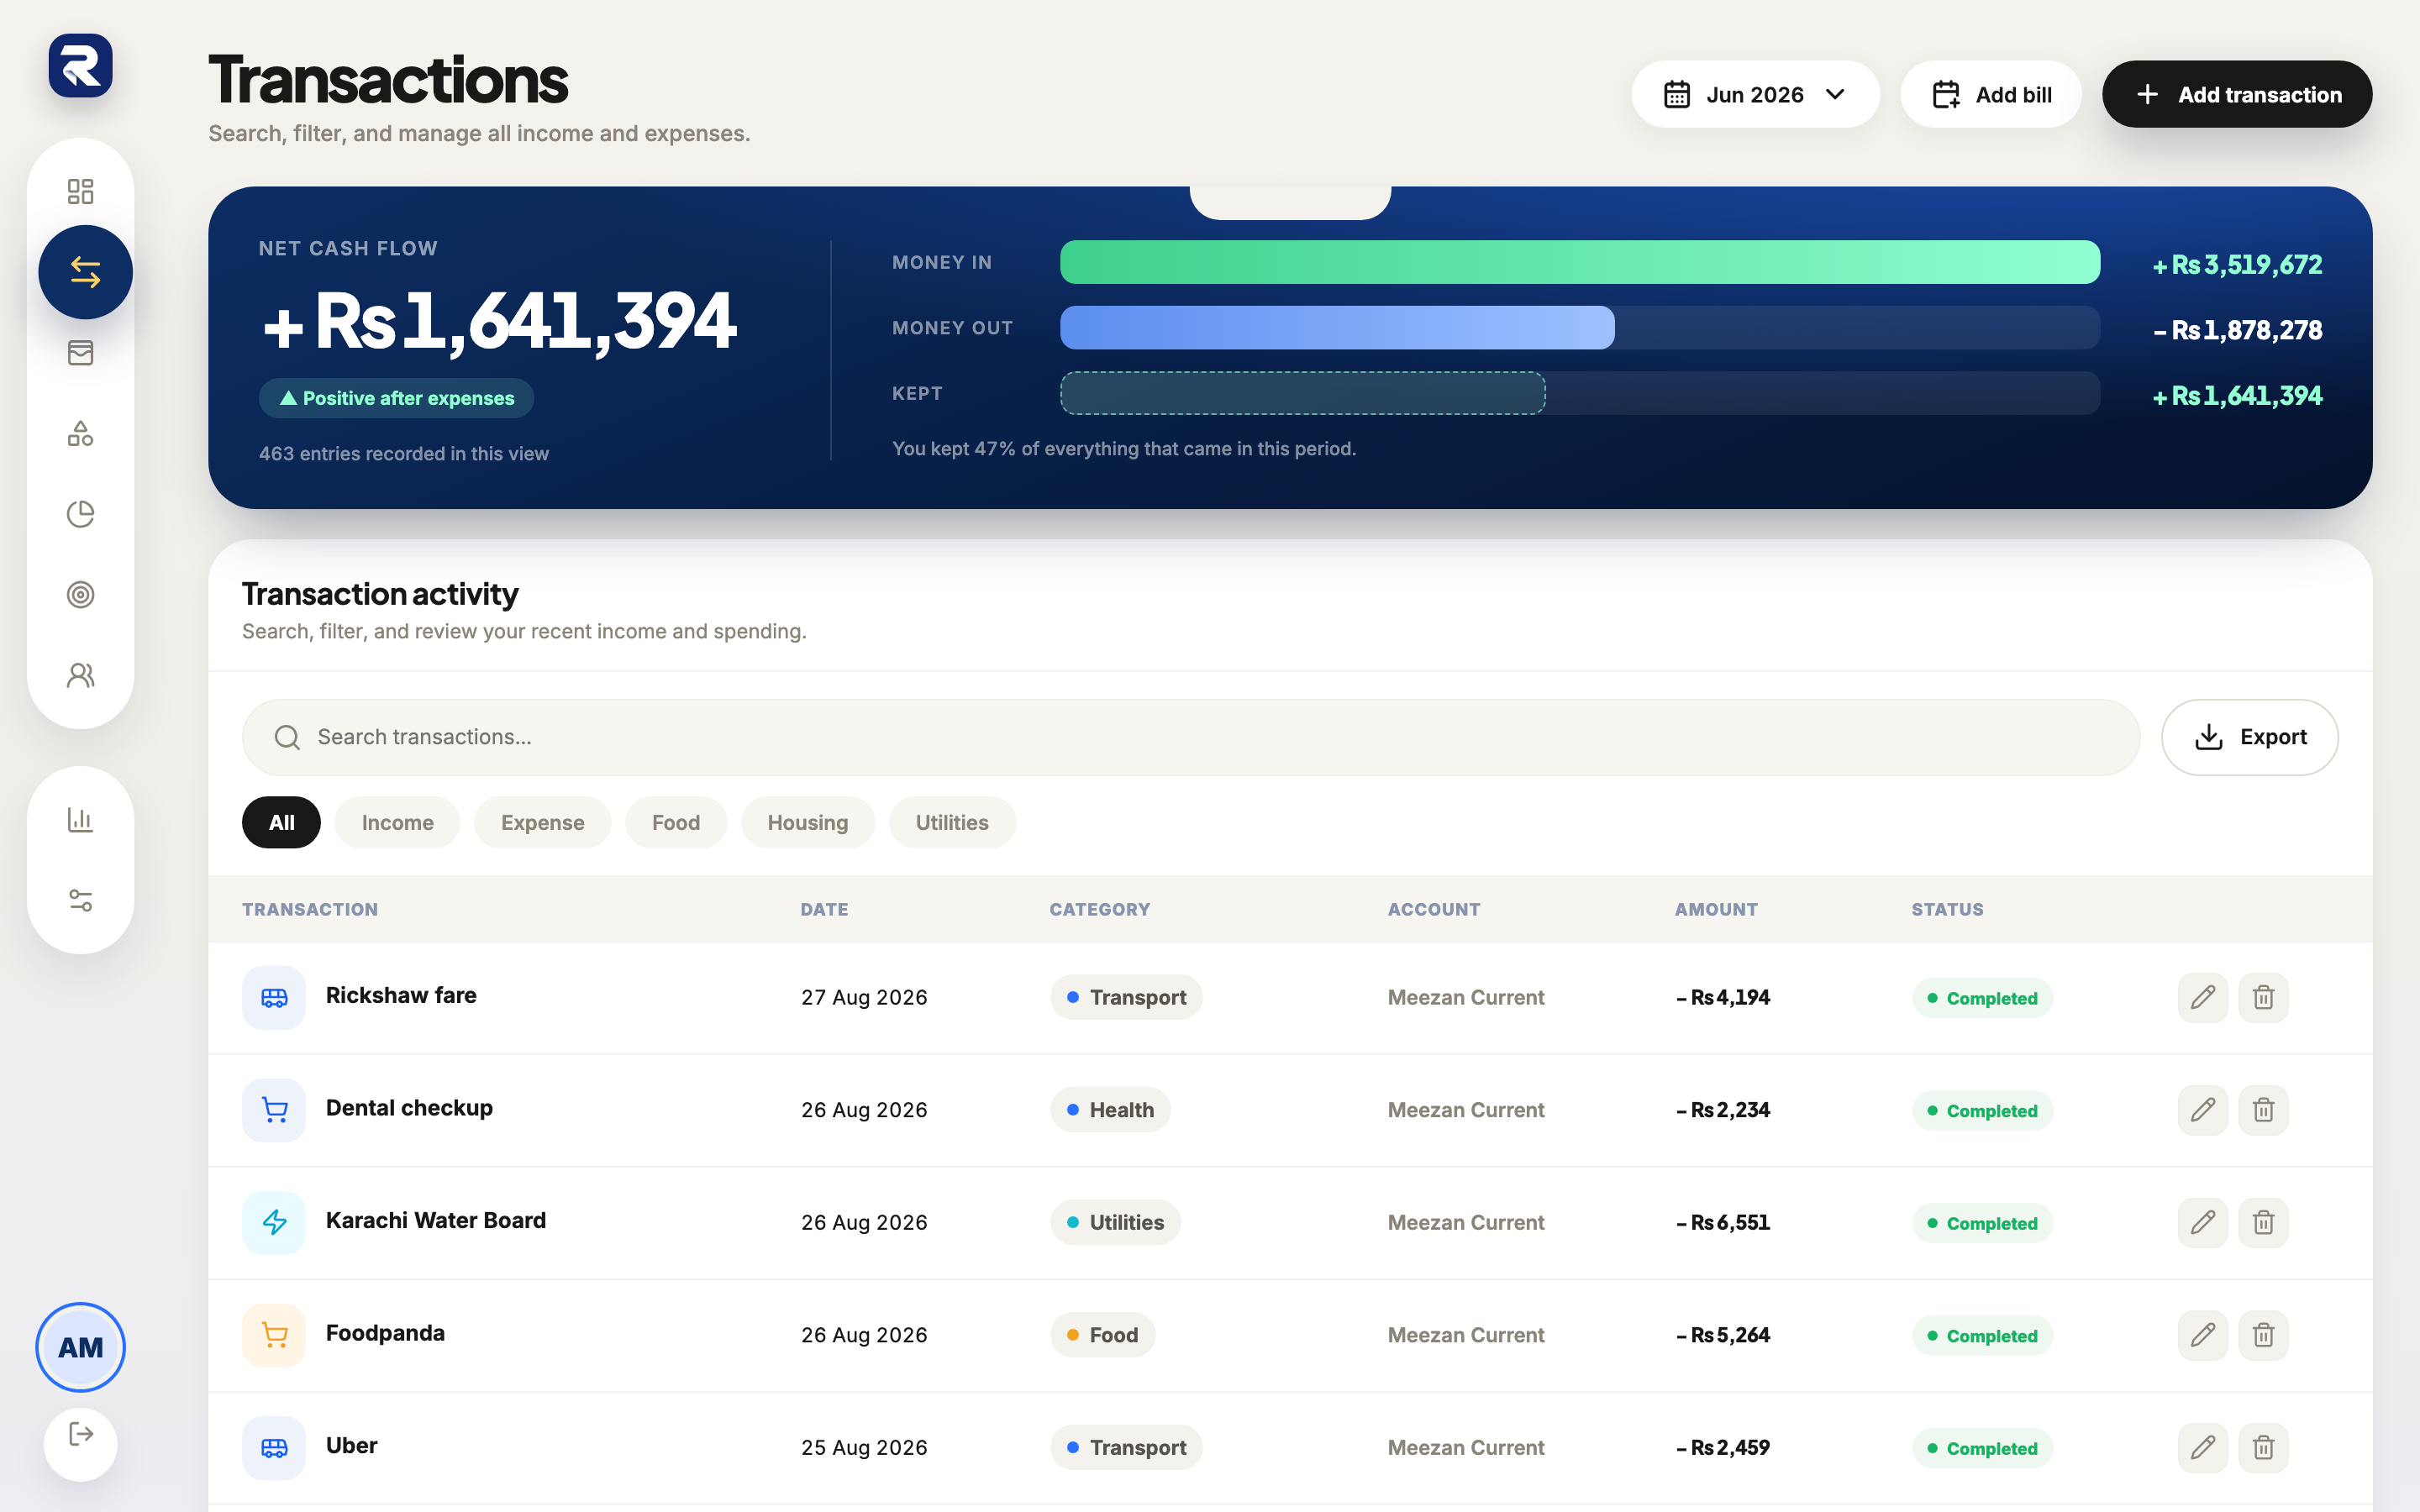
Practically: a negative amount, dated when the money actually arrived, categorised exactly as the original was.
What breaks if you call it income
Two things, and both of them matter more than the tidiness question.
| Recorded as | Clothing category shows | Month shows |
|---|---|---|
| Income | Rs 12,000 spent | Rs 12,000 earned that you did not earn |
| Negative in Clothing | Rs 0 spent | Nothing — correctly |
The category error is the one you will notice: a clothing budget that has been eaten by a purchase you returned, and a breakdown that says you spent money you did not spend.
The savings-rate error is the one you will not notice, and it is worse. Savings rate is computed from income against expenses. Adding Rs 12,000 to both sides leaves the difference unchanged but the ratio distorted — and every health score and trend built on that ratio moves with it. A few refunds a year is enough to make a savings rate drift by a couple of points for no reason at all.
The month-boundary problem
Refunds are slow. A return made on the 28th can land on the 6th of the following month, which means the purchase and its reversal fall in different reporting periods.
Record it when the money moved. That is the rule, and it is worth holding even though it produces an untidy result — a January that overstates clothing and a February that shows a negative. The alternative is backdating, which makes both months read beautifully and puts your account balance out by Rs 12,000 for six days. Balances are checkable against the bank; category totals are not. Never break the checkable one to tidy the other.
Three cousins of the refund
Partial refunds
Same treatment, smaller number. A Rs 3,000 credit against a Rs 12,000 order is a negative Rs 3,000 in the original category. Do not edit the original transaction down to Rs 9,000 — the history of what happened is worth more than a single clean line, and you will want it when the second credit arrives.
Cashback and rewards
Not a refund. Nothing was returned; you were paid for behaviour. Treat it as income, or as an offset against card fees if you want to see the card’s true net cost. What it should not do is reduce your grocery spending, which is what happens if you post it against the category that triggered it.
Compensation and goodwill credits
A refund for a service that was bad but delivered is a judgement call. If it makes the purchase cheaper, treat it as negative spending. If it is an apology unconnected to value received, income is closer. Decide once and be consistent; the exact answer matters far less than not alternating between them.
Frequently asked questions
Is a refund income?
No. Income is money you earned; a refund is money you never really spent. Recording it as income inflates both your earnings and your spending for the period.
How should I record a refund?
As a negative amount in the same category as the original purchase. The category total then shows what you actually kept.
What if the refund arrives in a different month?
Record it in the month it arrived, in the original category. Backdating it to match the purchase makes the two months tidy and your bank balance wrong.
Is credit card cashback a refund?
Not really. Nothing was returned — you were paid for using the card. Income, or a reduction of card fees, is closer to the truth than negative spending.
Make your money easier to understand.
Track expenses, plan budgets, and keep your goals in one clear view with Rakama.
Try Rakama free ↗